Theory 1
Write and .
Observe that the random variables and are “centered at zero,” meaning that .
Covariance
Suppose and are any two random variables on a probability model. The covariance of and measures the typical synchronous deviation of and from their respective means.
Then the defining formula for covariance of and is:
There is also a shorter formula:
To derive the shorter formula, first expand the product and then apply linearity.
Notice that covariance is always symmetric:
The self covariance equals the variance:
The sign of reveals the correlation type between and :
| Correlation | Sign |
|---|---|
| Positively correlated | |
| Negatively correlated | |
| Uncorrelated |
Correlation coefficient
Suppose and are any two random variables on a probability model.
Their correlation coefficient is a rescaled version of covariance that measures the synchronicity of deviations:
The rescaling ensures:
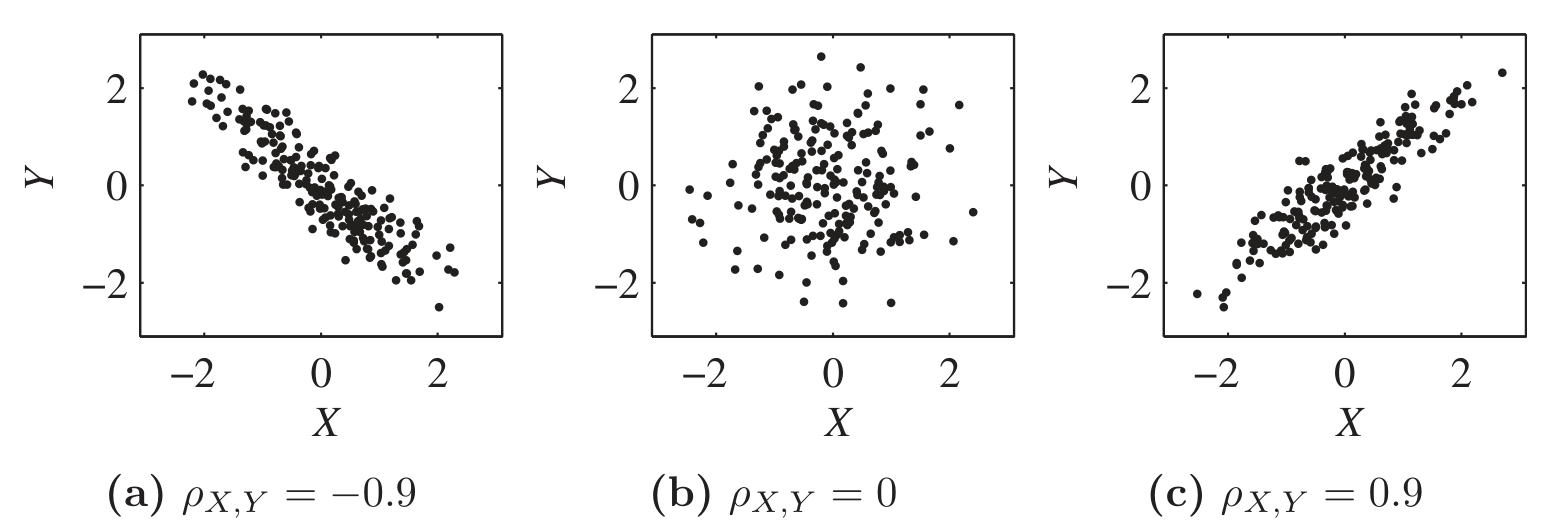
Covariance depends on the separate variances of and as well as their relationship.
Correlation coefficient, because we have divided out , depends only on their relationship.
Theory 2
Covariance bilinearity
Given any three random variables , , and , we have:
Covariance and correlation: shift and scale
Covariance scales with each input, and ignores shifts:
Whereas shift or scale in correlation only affects the sign:
Extra - Proof of covariance bilinearity
Extra - Proof of covariance shift and scale rule
Independence implies zero covariance
Suppose that and are any two random variables on a probability model.
If and are independent, then:
Proof:
We know both of these:
But , so those terms cancel and .
Sum rule for variance
Suppose that and are any two random variables on a probability space.
Then:
When and are independent:
Extra - Proof: Sum rule for variance
Extra - Proof that
(1) Create standardizations:
Now and satisfy:
Observe that for any . Variance can’t be negative.
(2) Apply the variance sum rule.
Apply to and :
Simplify:
Notice effect of standardization:
Therefore .
(3) Modify and reapply variance sum rule.
Change to :
Simplify: